
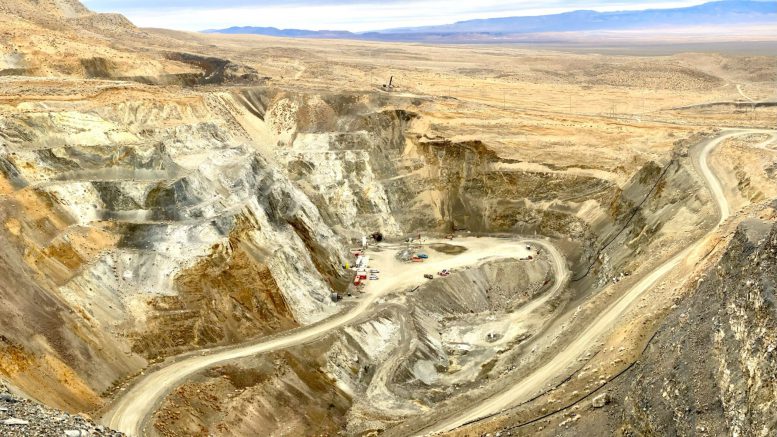
I-80 Gold (TSX: IAU; NYSE-A: IAUX) has outlined a larger resource, higher production and longer mine life at its Granite Creek underground mine in Nevada, although a new feasibility study also shows sharply higher costs than last year’s preliminary assessment.
The new study gives Granite Creek an after-tax net present value of $118 million (C$165 million) at a base-case gold price of $2,750 per oz., while life-of-mine all-in sustaining costs rise 42% to $2,273 per ounce. It also establishes initial reserves of 556,500 oz. and lifts measured and indicated resources 229% to 859,500 ounces.
“The feasibility study further de-risks Granite Creek’s role as a long-term source of high-grade feed for Lone Tree while preserving meaningful exploration upside through South Pacific extensions and the largely untested CX Zone,” National Bank of Canada Capital Markets mining analyst Don DeMarco said in a note Tuesday. “Base-case economics remain relatively modest, weighted by elevated costs.”
Granite Creek is a central piece of i-80’s plan to grow from about 50,000 oz. of annual production into a mid-tier Nevada gold producer. The company secured a $500-million financing package in February to fund the first two stages of a development plan targeting roughly 300,000 to 400,000 oz. of annual production before eventually reaching about 600,000 ounces.
Higher costs
By comparison, the March 2025 preliminary economic assessment forecast life-of-mine all-in sustaining costs of $1,597 per ounce. Costs would fall to $1,915 per oz. during the higher-output 2028-32 period.
The impact becomes clearer when the two studies are compared using the same gold price. At $3,000 per oz., the new study generates an after-tax NPV of $193 million compared with $373 million in the PEA sensitivity, reflecting higher costs, DeMarco said. He maintained an outperform rating and C$4 target on i-80.
Shares in i-80 Gold gained 3.3% to C$2.51 apiece on Monday morning in Toronto, valuing the company at C$2.17 billion. They’ve traded in a 52-week range of C$1.25 to C$3.04.
Total capital and closure costs rise to $145 million from $112 million in the PEA. That includes $83 million in sustaining capital, a $49-million allocation for refurbishing the Lone Tree plant and $12.7 million for closure and reclamation.
Against that, total recovered production increases to 485,000 oz. from about 418,000 oz. in the PEA, while average recovery rises to 87% from 78%.
Granite Creek is already operating as i-80 ramps the underground mine towards commercial production, which it expects to achieve in late 2026. The mine produced 22,977 oz. of gold last year and 17,532 oz. in the first half of 2026, including 8,634 oz. in the second quarter. The 8.5-year mine plan calls for output of 30,000 to 40,000 oz. this year, rising to about 75,000 oz. annually from 2028 through 2032 after the Lone Tree plant starts up.
“The mine plan benefits from additional working faces, improved geological definition and successful drilling in the South Pacific Zone,” DeMarco said. “Costs are expected to decline from about 2028 with commissioning of the Lone Tree facility.”
Reserve boost
The study establishes an initial 2.2 million proven and probable tonnes grading 7.87 grams gold per tonne for 556,500 oz. contained gold.
Resources also increased substantially. Granite Creek now hosts 3.73 million measured and indicated tonnes grading 7.17 grams gold per tonne for 859,500 oz., up 229% from the PEA, while 893,000 inferred tonnes grade 7.06 grams for 202,800 ounces. Much of the decline in inferred ounces reflects conversion into higher-confidence categories.
“The drill program successfully delineated and expanded the mineralized zones, demonstrated continuity within the mineralized structures, and identified a number of additional prospective targets that suggest the potential for further mineral resource growth,” President and CEO Richard Young said in a release.
“With the Lone Tree Plant anticipated to be operational by the end of 2027, these assets are expected to support i-80 Gold’s transformation into a Nevada-focused mid-tier producer generating strong free cash flow.”
Cash flow
The Granite Creek study forecasts $238 million of net cash flow during the five years from 2028 through 2032, after Lone Tree is expected to start processing its ore. That includes $92 million in 2028 and between $28 million and $40 million annually over the following four years.
At the company level, i-80 expects its first two development stages to lift annual production to 300,000–400,000 oz. by 2031 and generate enough operating cash flow to fund the third stage, centred on the Mineral Point open pit.
Until Lone Tree is commissioned in the fourth quarter of 2027, i-80 plans to use third-party processing before stockpiling some Granite Creek ore ahead of startup. The refurbished autoclave is intended to become the hub of the company’s Nevada operations, treating material from Granite Creek and the Archimedes underground project at Ruby Hill.
Be the first to comment on "I-80’s Granite Creek resources triple, costs jump"